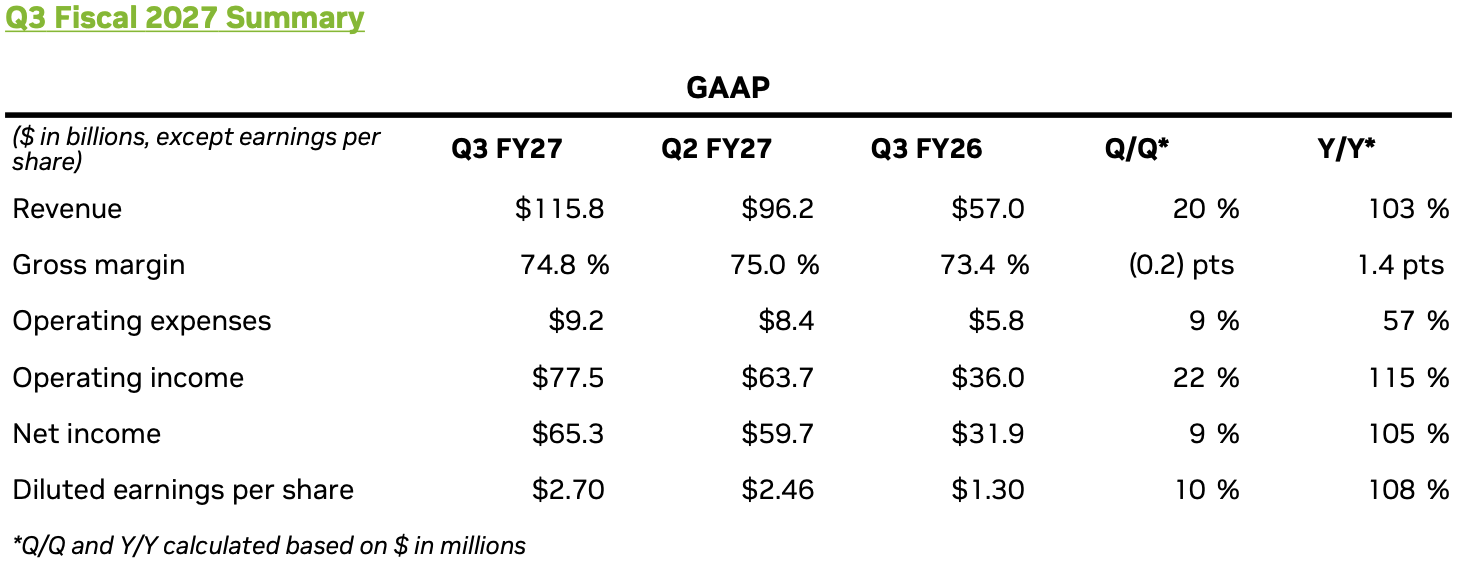
For the first time in its 33-year history, Nvidia on Tuesday reported quarterly financial results without Jensen Huang at its helm or on the call, after its cofounder and longtime chief executive departed five days ago. To no one's surprise, Nvidia continues to set new financial records as demand for its AI accelerators shows no signs of slowing down. The company reported revenue of $115.8 billion for the third quarter of its fiscal 2027, with its latest Vera Rubin platform generating $20 billion. Meanwhile, its supply commitments surged to $390 billion.
'Momentum is real'
"Our momentum is real. NVIDIA is an exceptional technology leader, powered by the relentless innovation of our people," said Colette Kress, interim chief executive and chief financial officer of Nvidia. "Vera Rubin is off to an explosive start, our roadmap is on track, and our ambition has never been greater."
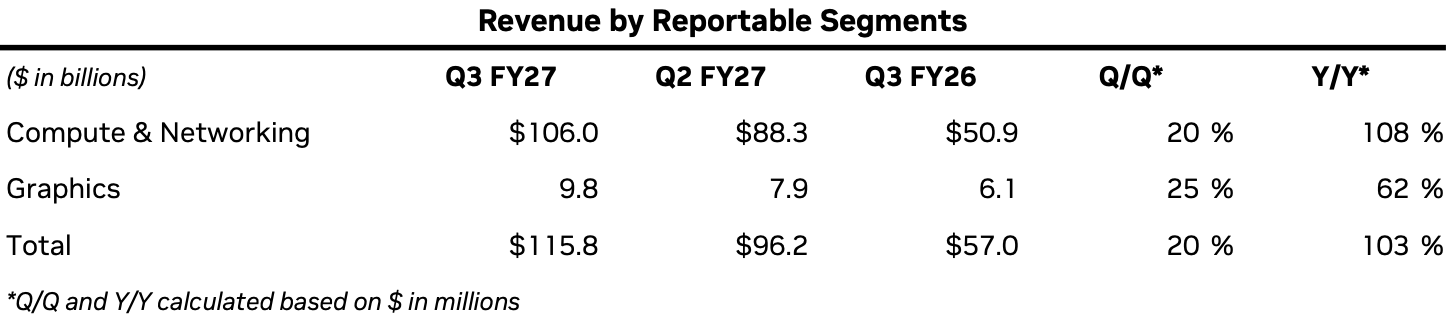
For the third quarter of fiscal 2027, which ended on October 25, 2026, Nvidia posted revenue of $115.844 billion, an increase of 20% sequentially and 103% year-over-year. The company's net income reached $65.287 billion, up 105% from the same quarter last year, while gross margin hit 74.8%. Revenue from the Compute & Networking segment totaled $106 billion, up 20% quarter-over-quarter and 108% year-over-year. Meanwhile, the Graphics segment generated $9.8 billion, a sequential increase of 25% and 62% compared with the same period a year ago.
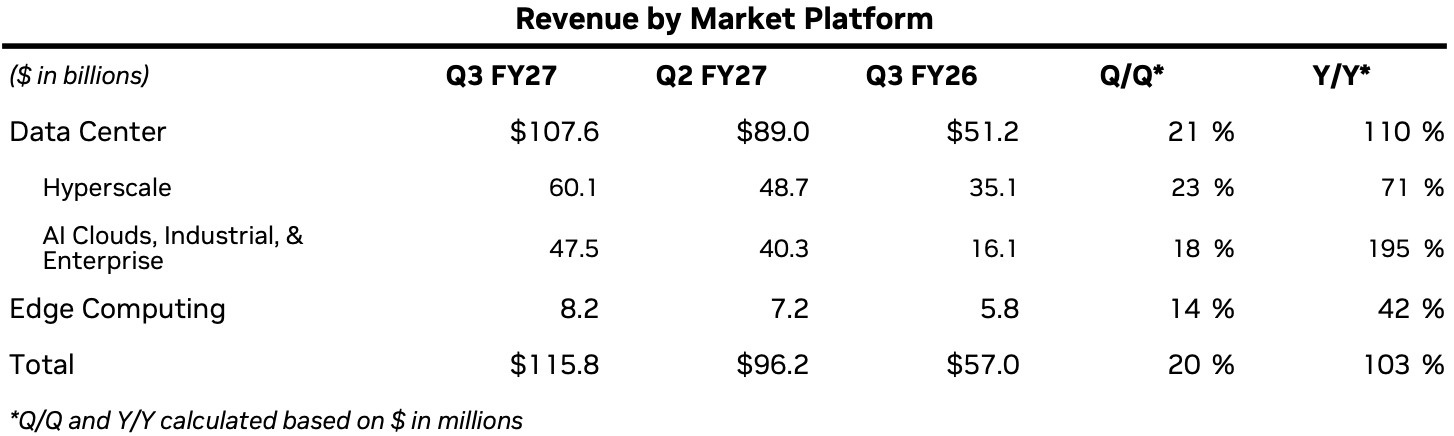
As expected, Nvidia's results during the quarter were primarily driven by its Data Center business, which generated $107.6 billion in revenue (and accounted for approximately 93% of the company's sales), up 21% sequentially and 110% YoY. Hyperscale customers accounted for $60.1 billion, an increase of 23% QoQ and 71% YoY, while sales to AI Clouds, Industrial & Enterprise customers reached $47.5 billion, up 18% sequentially and 195% compared to the same period last year. Although hyperscalers remain Nvidia's largest customer category, demand from AI cloud providers, industrial companies, and enterprises continues to grow considerably faster on an annual basis. Meanwhile, Edge Computing revenue reached $8.2 billion, up 14% sequentially and 42% year-over-year.
One of the main contributors to Nvidia's growth was its Vera Rubin platform, which generated nearly $20 billion in revenue in its first quarter of production shipments, which Nvidia described as the fastest product ramp in its history. The company also reported strong demand for standalone Vera CPUs and continued sales growth for Blackwell Ultra. According to Nvidia, its hyperscale partners brought Vera Rubin systems into production in approximately one month, which is two times faster than the previous-generation Grace Blackwell platform.
"Vera Rubin is off to an extraordinary start: in its first quarter of production shipments, the Rubin platform generated nearly $20 billion in revenue, making it the fastest product ramp in Nvidia's history," Kress said. "We continue to see very strong demand for Vera and expect total CPU revenue to more than double in FY2028."
Supply commitments reach $390 billion
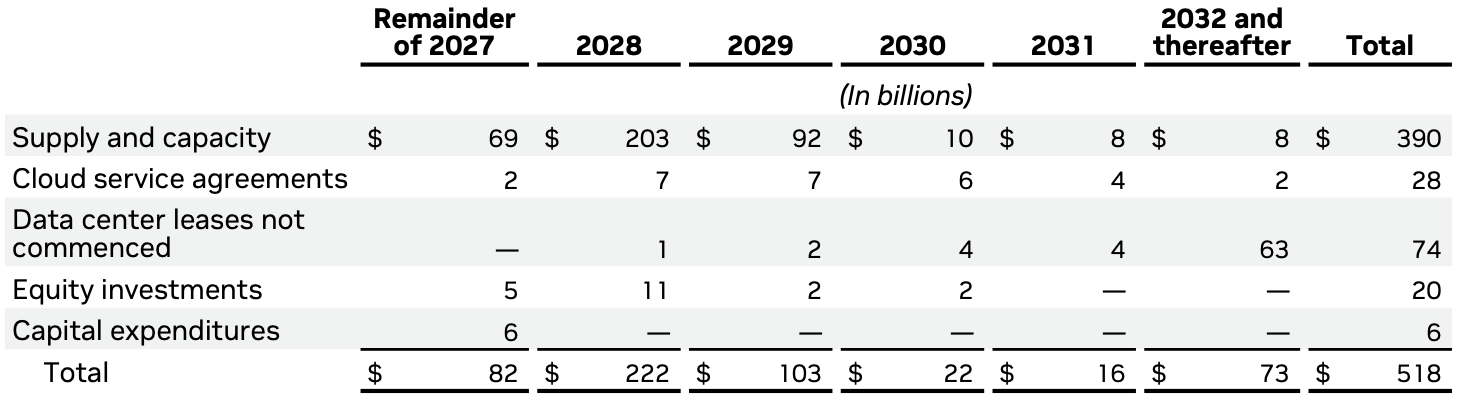
To support the expected growth of its AI infrastructure business, Nvidia has substantially increased its long-term procurement obligations. The company's supply and capacity commitments reached $390 billion at the end of Q3 FY2027, compared with $279 billion three months earlier and $119 billion at the end of Q1. Nvidia attributed the latest increase primarily to multiyear memory procurement agreements.
The company expects to fulfill $69 billion of these commitments during the remainder of FY2027 (which ends in late January), followed by $203 billion in FY2028 and $92 billion in FY2029. Another $26 billion is scheduled for FY2030 and beyond. In other words, Nvidia has already committed to purchasing $390 billion worth of components and manufacturing capacity through the end of FY2030, though given the fact that its purchases in FY2028 are set to exceed $200 billion, expect its procurements in FY2030 to be higher.
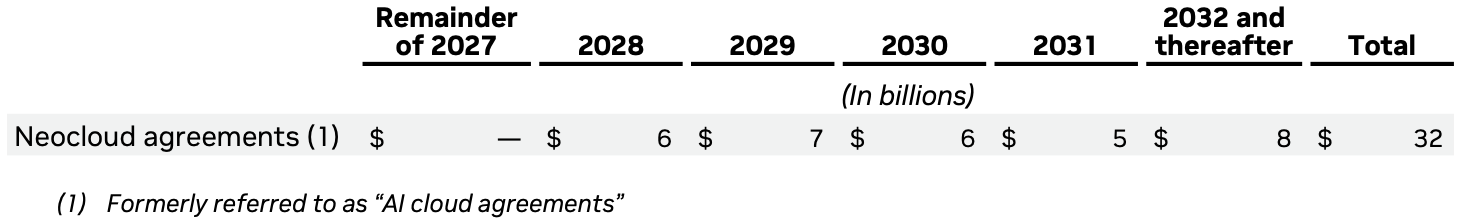
The commitments reflect Nvidia's efforts to ensure that its suppliers can manufacture sufficient quantities of advanced processors, memory, substrates, and packaging components. In addition to its existing agreements with partners like TSMC, Micron, Samsung, and SK hynix, Nvidia on Wednesday announced new partnerships with Samsung Electro-Mechanics and Kinsus for substrates, as well as SPIL for advanced packaging. In addition, the company disclosed agreements with Amkor, Ibiden, KYEC, and Unimicron.
During the earnings call, Kress said that demand for Nvidia's products continues to exceed available supply, prompting the company to work with manufacturing partners to expand production capacity. She also indicated that Nvidia could provide suppliers with prepayments or other financial assistance to accelerate capacity expansion.
Although these procurement commitments are gargantuan, Nvidia expects demand for its AI infrastructure to remain strong, which will justify the expenditures. The company raised its revenue growth forecast for FY2028 from approximately 70% to 75% due to stronger demand and additional manufacturing capacity that it expects to secure.
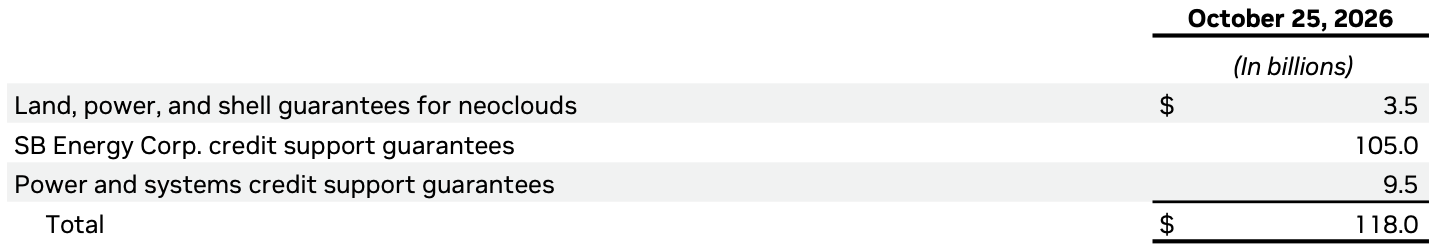
In addition to its supply commitments, Nvidia disclosed $32 billion in agreements with neocloud providers that allow it to earn revenue from hardware sales and participate in cloud rental revenue above a guaranteed minimum. Meanwhile, the company's maximum financial exposure under various guarantees reached $118 billion, including $105 billion in credit support for the PORTS-Pike AI data center campus in Ohio, which will serve OpenAI under 20-year leases.
In total, Nvidia's commitments reached $540 billion as of early Q4 FY2024.
2028 pricing strategy and beyond
Nvidia currently absorbs higher component and manufacturing costs to honor existing purchase orders and maintain previously agreed prices for its customers. As a result, the company expects its GAAP gross margin to decline from 74.8% in Q3 FY2027 to 71% – 72% in Q4, which it considers the bottom of the current margin cycle.
Going forward, Nvidia plans to introduce revised pricing in FY2028 to help offset higher supply costs and restore profitability, which is when the company expects gross margins to recover to 72% – 73% next fiscal year, although it has not disclosed the magnitude of its planned price adjustments or the products they will affect.
"We thought about in terms of our prices and pieces of that, and a lot of the costs were some of the things that we absorbed in those numbers that we included," Kress said. "What we provided here in Q4 is our bottom. If you recall, that was our bottom as we honored many of the different POs that we had already received from our customers, and we just wanted to make sure that was held solid as we moved to a new pricing, as we moved into the new year."
Perhaps more importantly is that Colette Kress largely sidestepped the question about custom AI accelerators and their potential impact on Nvidia's pricing power. During the conference call, an analyst asked whether Nvidia would accept lower margins to protect its market share against custom AI accelerators developed by hyperscalers. The interim CEO avoided directly addressing whether competition from custom silicon could undermine Nvidia’s competitive position, leaving considerable room for speculation.
Nvidia expects $130 billion in Q4
For the fourth quarter of fiscal 2027, Nvidia projects revenue of approximately $130 billion ±3%, which would represent an increase of about 12% sequentially. The company expects GAAP gross margin of 71% to 72% and GAAP operating expenses of approximately $11 billion during the quarter. Nvidia’s forecast excludes Data Center compute revenue from China and accounts for an additional week in the quarter. While Nvidia expects its gross margin to decline during the Vera Rubin transition, Kress said that the company anticipates a recovery to 72% – 73% in FY2028.