AI & ML
Online Conformal Prediction via Universal Portfolio Algorithms
arXiv stat.ML0 views
arXiv:2602.03168v2 Announce Type: replace Abstract: Online conformal prediction (OCP) seeks prediction intervals that achieve long-run $1-\alpha$ coverage for arbitrary (possibly adversarial) data streams, while remaining as informative as possible. Existing OCP methods often require manual learning-rate tuning to work well, and may also require algorithm-specific analyses. Here, we develop a general regret-to-coverage theory for interval-valued OCP based on the $(1-\alpha)$-pinball loss. Our first contribution is to identify \emph{linearized regret} as a key notion, showing that controlling it implies coverage bounds for any online algorithm. This relies on a black-box reduction that depends only on the Fenchel conjugate of an upper bound on the linearized regret. Building on this theory, we propose UP-OCP, a parameter-free method for OCP, via a reduction to a two-asset portfolio selection problem, leveraging universal portfolio algorithms. We show strong finite-time bounds on the miscoverage of UP-OCP, even for polynomially growing predictions. Extensive experiments support that UP-OCP delivers consistently better size/coverage trade-offs than prior online conformal baselines.
Source:https://arxiv.org/abs/2602.03168PreviousVariational Estimators for Node Popularity ModelsNextTight Generalization Bounds for Noiseless Inverse Optimization
Related posts

Where an e-commerce explainer video belongs, and what to show in it
0dev.to

How to explain a crypto product on video without sounding like a pitch
0dev.to

Why Europe's Freezer Hacks Spread So Far, So Fast
0Dark Reading
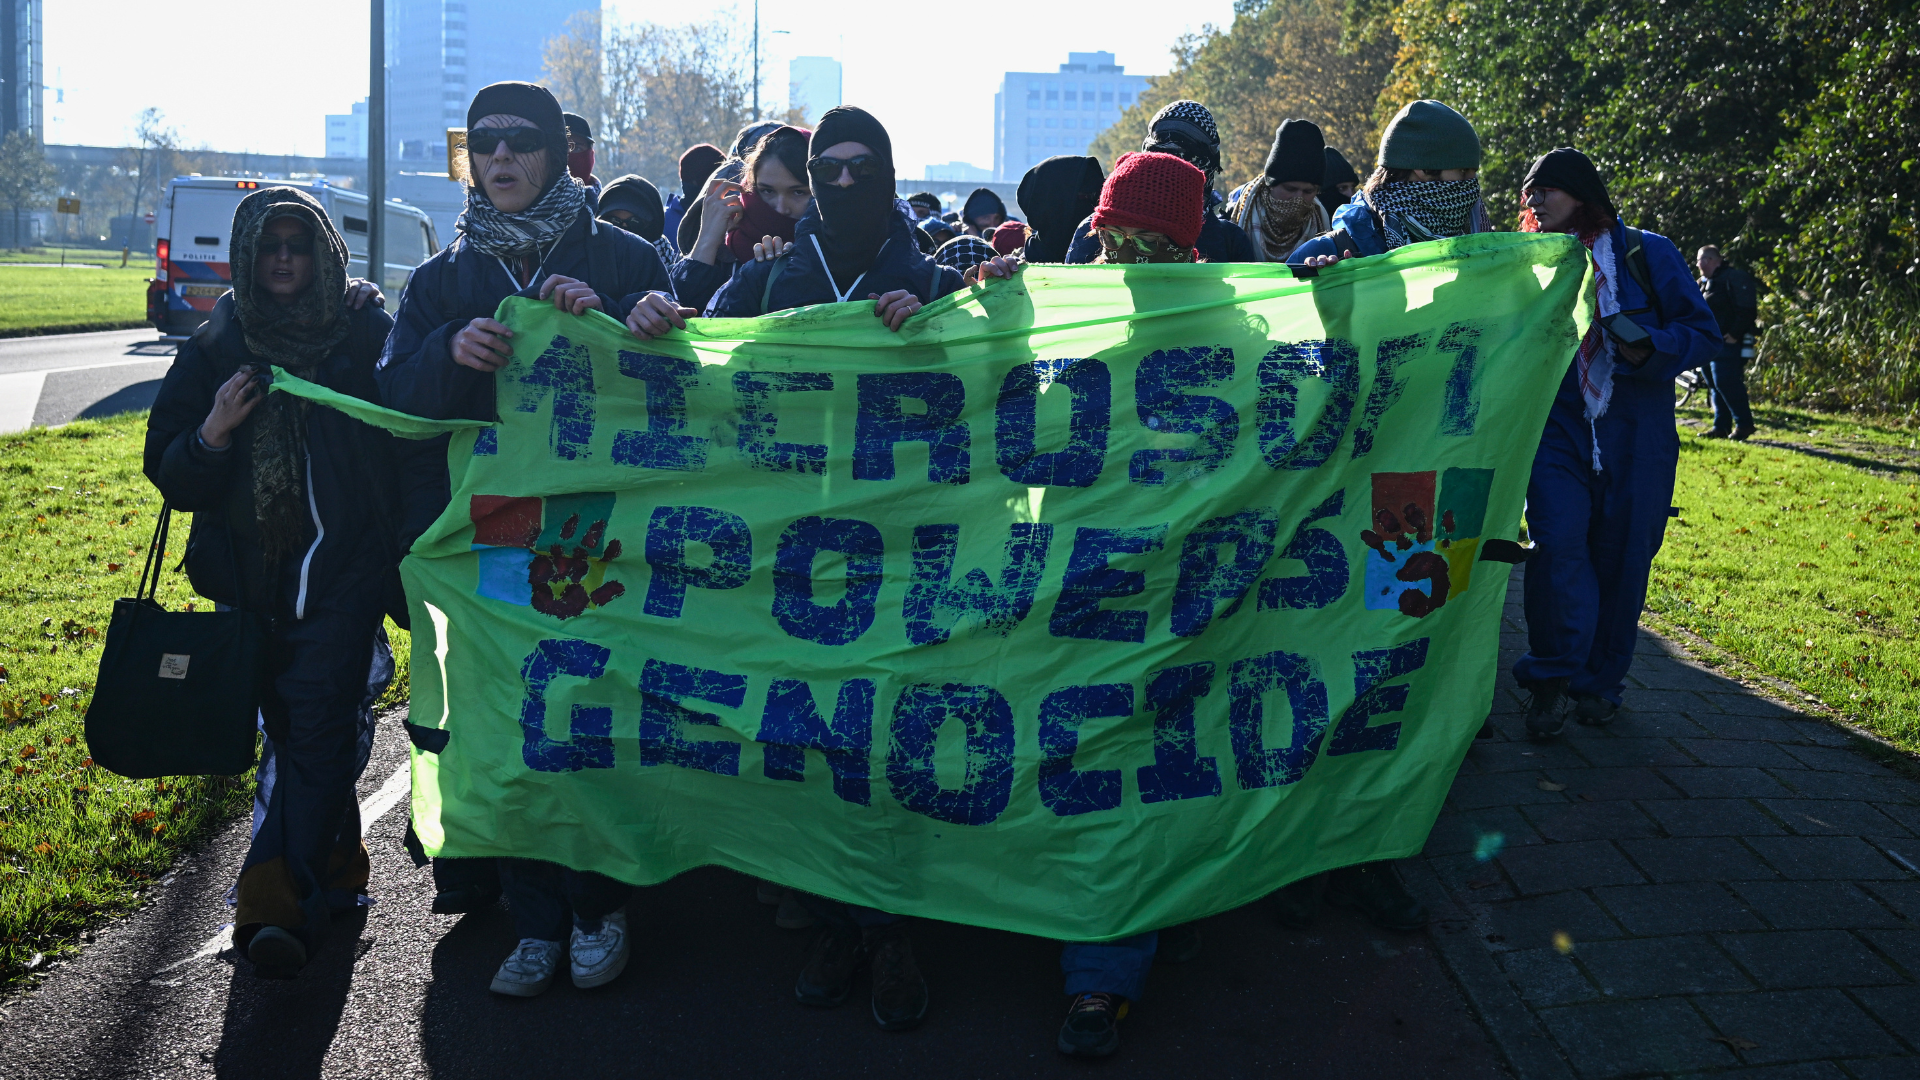
Protesters storm Microsoft AI data center construction site
0Tom's Hardware

The Download: a humanoid cleans house and Samsung builds for the AI boom
0MIT Technology Review

How Remedy designed Control Resonant’s wildest mission: ‘Anything kind of goes’
0The Verge