General
Outlier-Robust Multi-Output Gaussian Processes
arXiv stat.ML0 views
arXiv:2510.26401v2 Announce Type: replace Abstract: Multi-output Gaussian process (MOGP) regression allows modelling dependencies among multiple correlated response variables. Similarly to standard Gaussian processes (GPs), MOGPs are sensitive to model misspecification and outliers, which can distort predictions within individual outputs. In the multi-output case, this situation can be further exacerbated as anomalous observations in one response can adversely influence predictions for other correlated outputs. To handle this situation, we propose R-MOGP, an MOGP that is provably robust to outliers in any individual response. Our approach preserves conjugacy, achieving robustness without sacrificing computational efficiency, and integrates naturally with sparse variational inference for scalability. Empirically, we show that R-MOGP achieves performance comparable to existing state-of-the-art robust MOGPs at a fraction of their computational costs.
Source:https://arxiv.org/abs/2510.26401PreviousOptimal In-context Adaptivity and Distributional Robustness of TransformersNextSparse Network Inference under Imperfect Detection and its Application to Ecological Networks
Related posts

Fable 5.2 one-shotted my nephew's dream game
0Hacker News
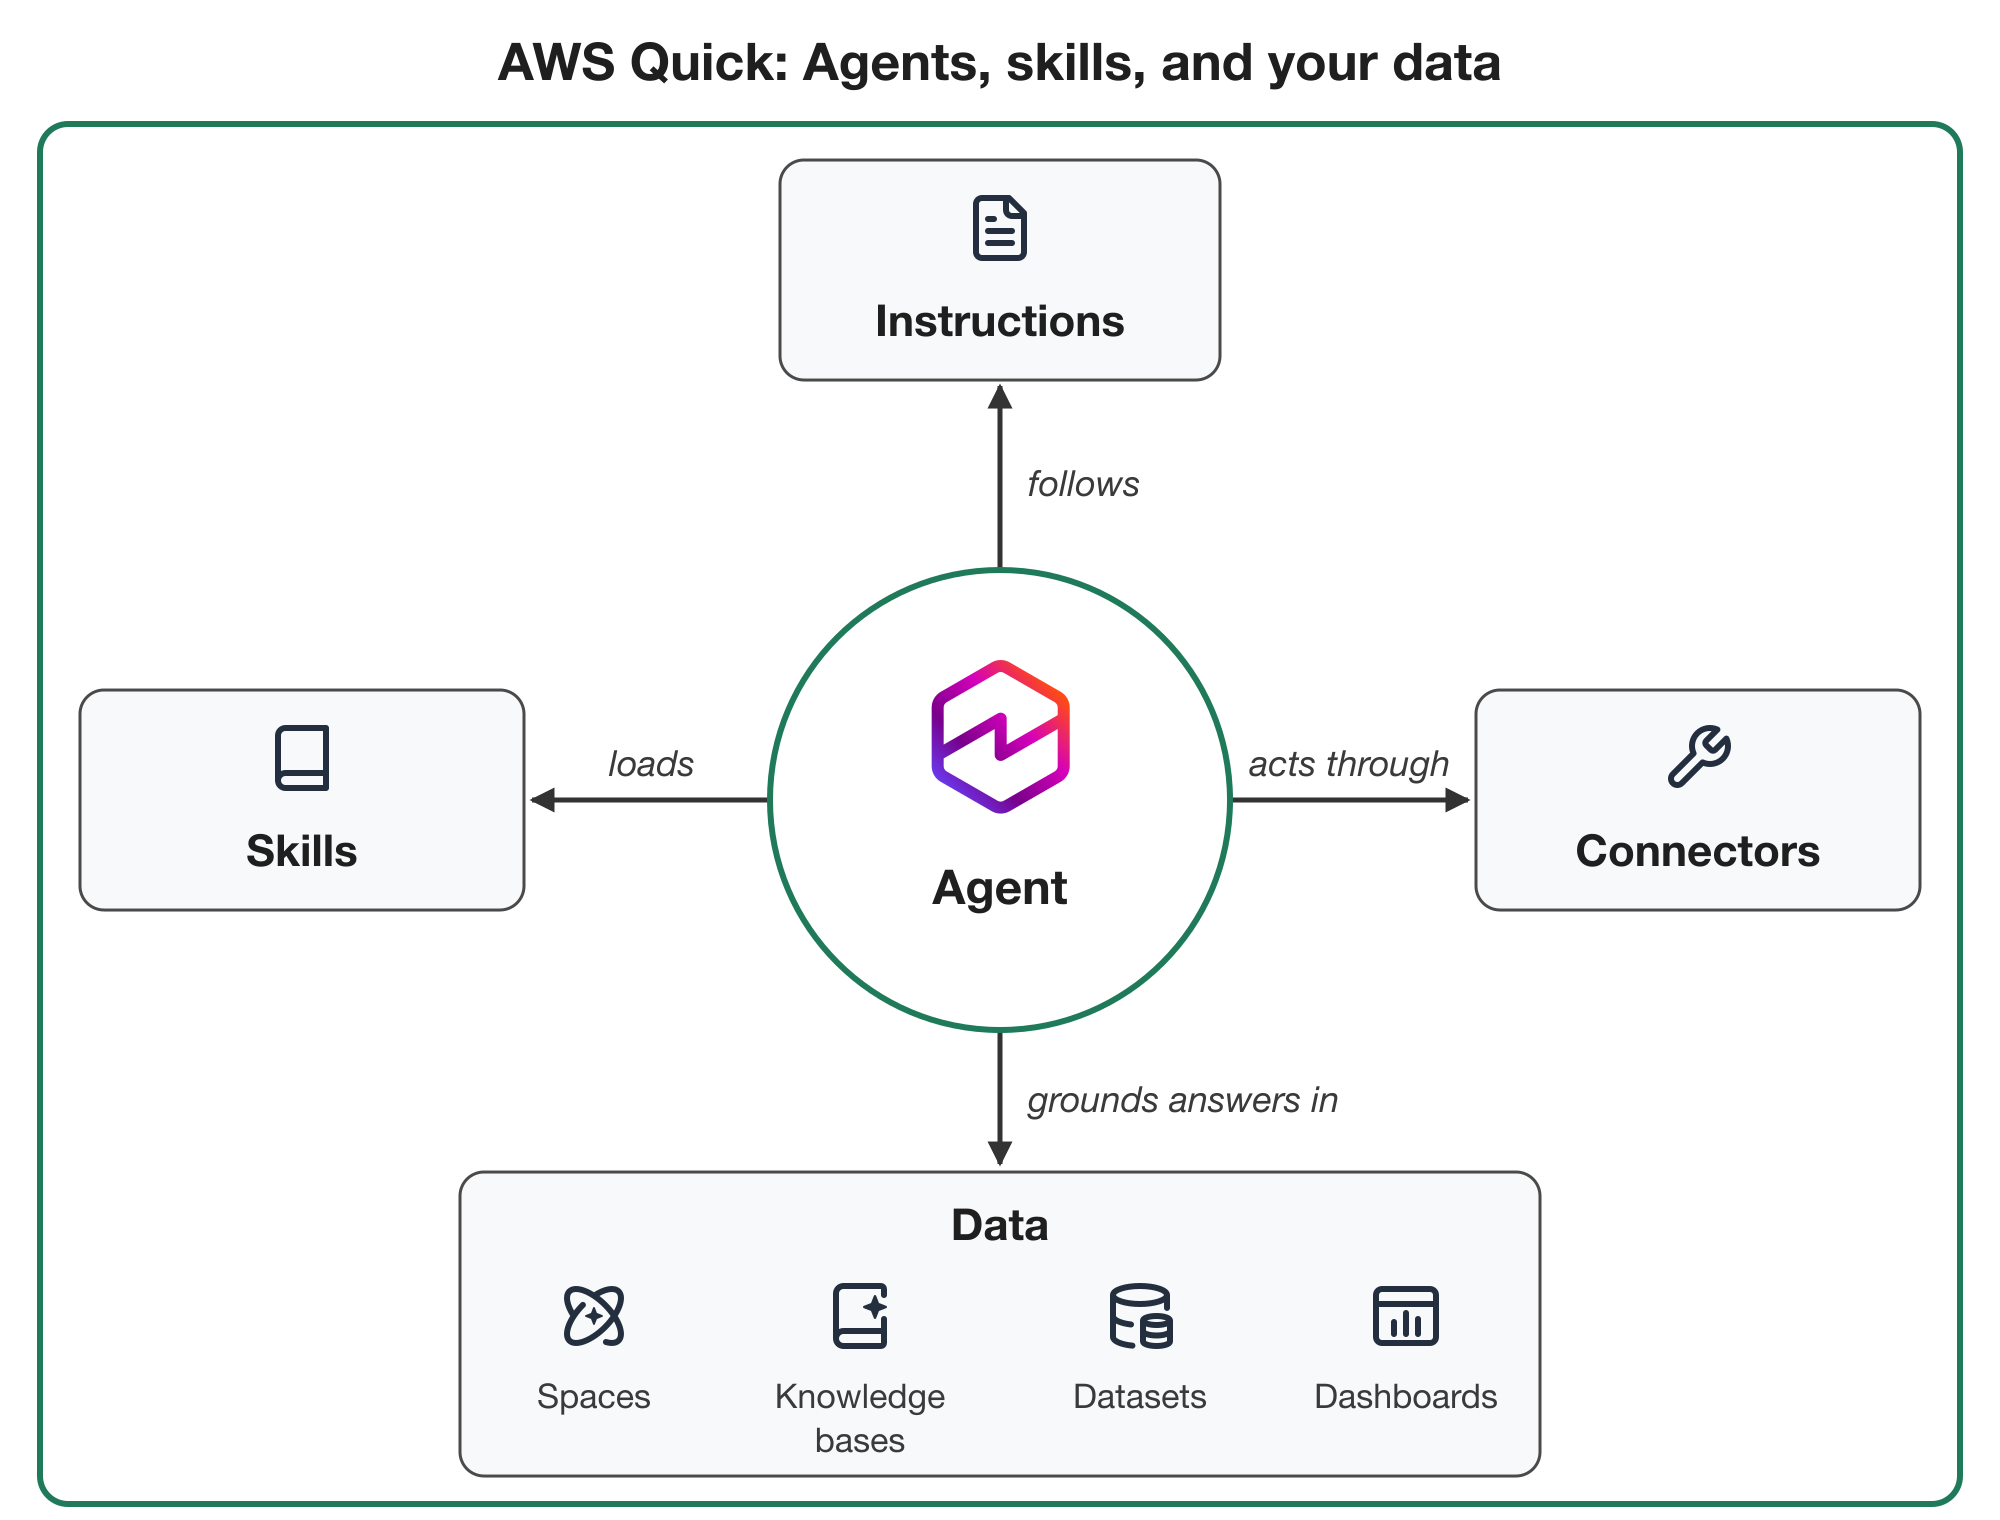
How skills and agents work in AWS Quick
0AWS Machine Learning Blog

Trump's ties to Nvidia's Huang scrutinized after foreign intelligence concerns
0Hacker News New

How to Become a Lost
0Hacker News New

HeyWhatsThat – Calculate viewshed and panorama for any point on Earth (2022)
0Hacker News New

SVG sky map with Ruby and Astronoby
0Hacker News New